AnitaB.org Cancels Grace Hopper Celebration 14 Days Out After Losing $14.6M and Half Its Attendees
20 Oct 2026
AnitaB.org cancelled the 2026 Grace Hopper Celebration 14 days out after a $14.6M loss and a halving of attendance. How women in tech lost their biggest stage.
Mean-Field LIBOR Models Offer Reliable Bounds for Life Insurance Valuation, Study Finds
12 Feb 2026
A study on mean-field LIBOR models shows how insurers can estimate future discretionary benefits with greater accuracy and reduced simulation error.
How Public Balance Sheet Data Can Be Used to Estimate Life Insurance Guarantee Costs
12 Feb 2026
Public balance sheet data is used to estimate life insurance guarantee costs, comparing model bounds with Allianz Life’s reported figures.
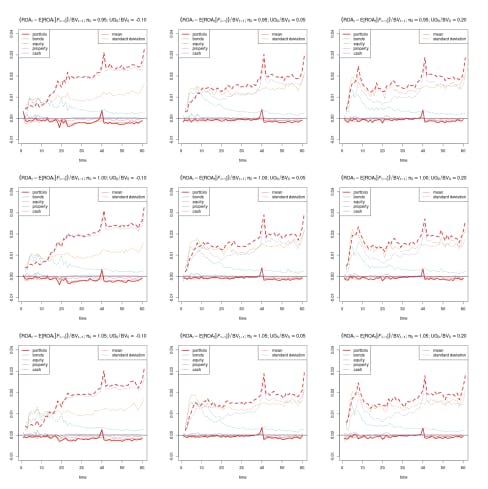
Estimating Future Discretionary Benefits Without Monte Carlo Simulation
12 Feb 2026
A deterministic framework for estimating future discretionary benefits in life insurance, offering tight bounds without Monte Carlo simulation.
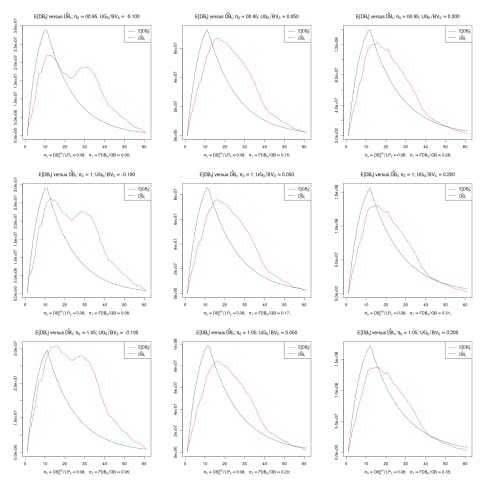
Testing Actuarial Assumptions With Realistic Life Insurance Data
12 Feb 2026
Numerical evidence testing key actuarial assumptions in life insurance models, with implications for surplus dynamics and the cost of guarantees.
The Mean-field Libor Market Model
11 Feb 2026
Mean-field Libor market model controls variance to reduce rate “blow-ups,” with conditions for existence, uniqueness, and particle-based simulation.
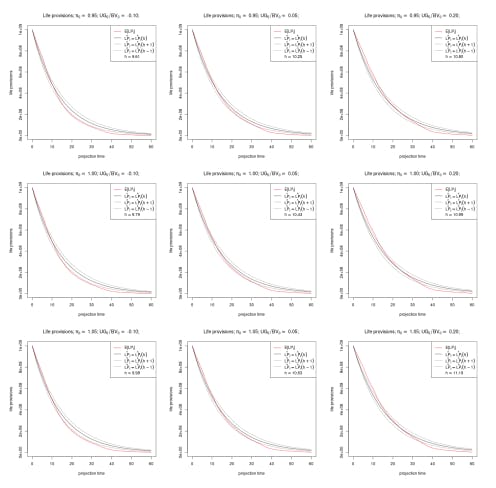
How Numerical ALM Models Value Future Discretionary Benefits in Life Insurance
11 Feb 2026
A technical walkthrough of numerical ALM modeling for life insurance, combining Monte Carlo simulations, ESGs, and profit-sharing rules under Solvency II.
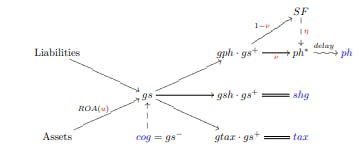
How Profit Participation Shapes Risk and Returns in Traditional Life Insurance
11 Feb 2026
A technical deep dive into profit-participating life insurance, explaining asset-liability dynamics, surplus allocation, and optimal control strategies.
Valuing Profit-Participating Life Insurance Liabilities in a Solvency II Framework
11 Feb 2026
A market-consistent framework for valuing profit-participating life insurance under Solvency II, combining interest rate modeling and FDB bounds.